

Finance leases, hire-purchase and VAT: our op-ed in Daf Magazine
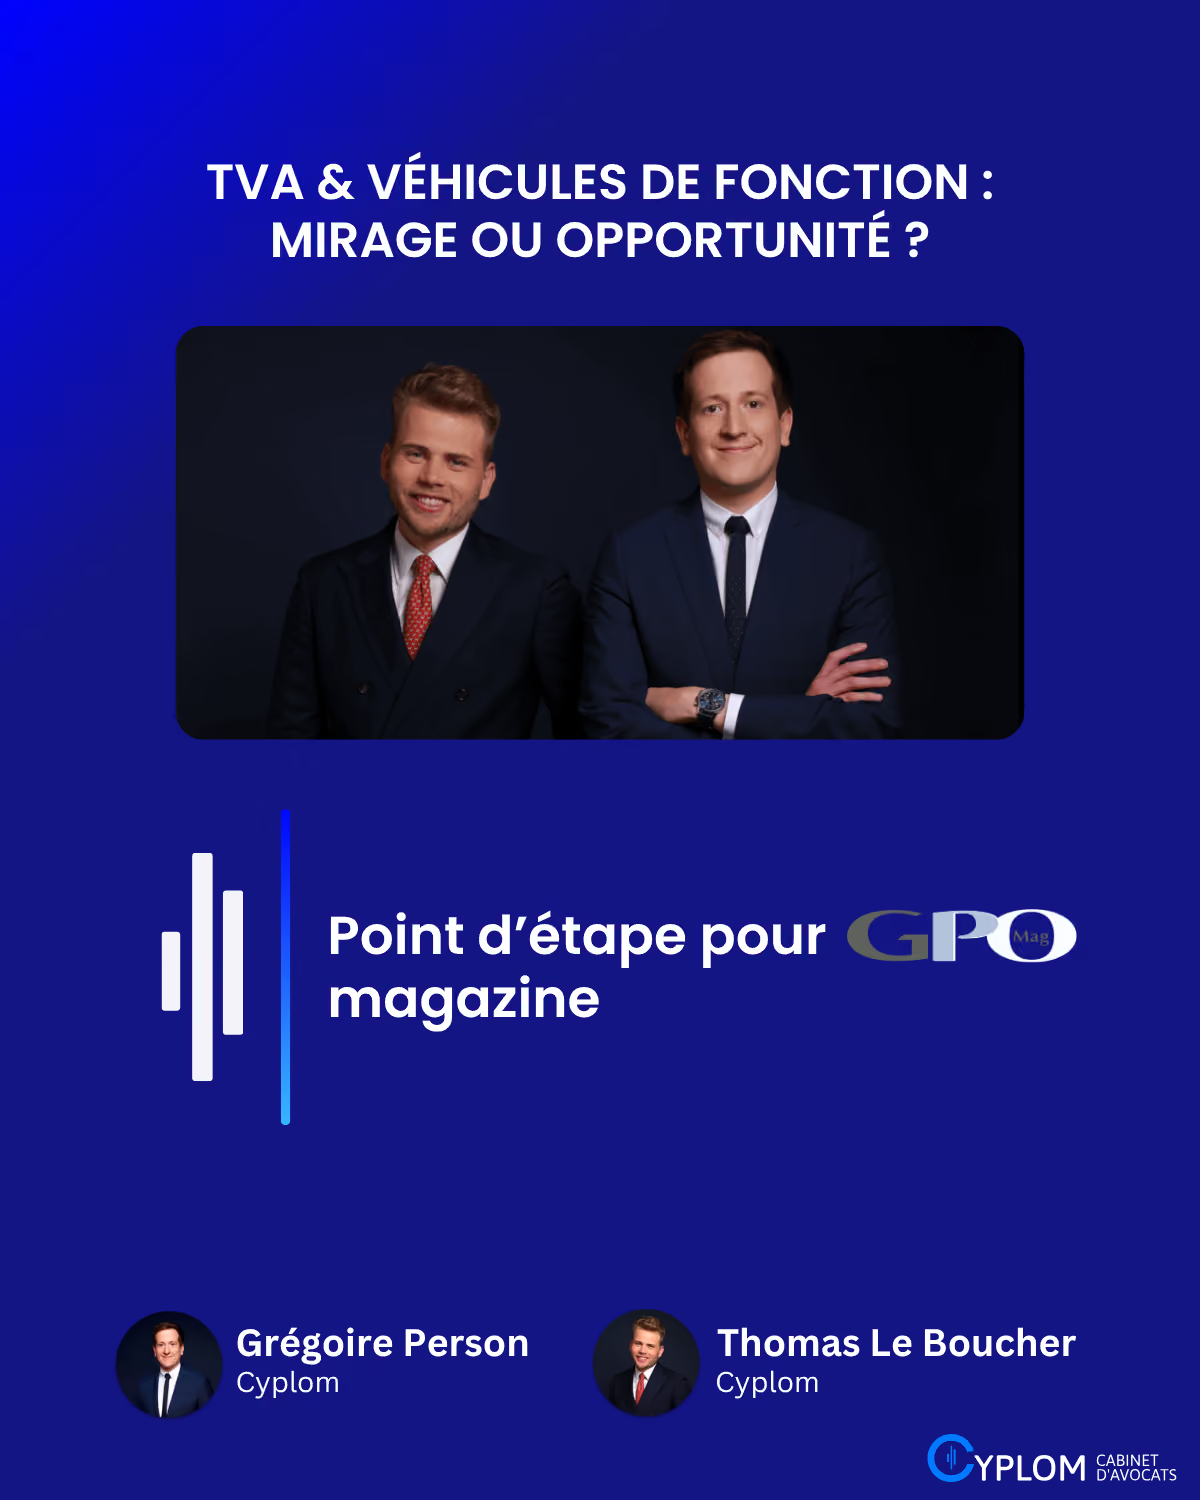
Grégoire Person on Article L. 211-36 of the CIBS, which could turn certain finance lease and hire-purchase contracts into supplies of goods on delivery.
What the op-ed is about
On 1 September 2026 Daf Magazine published an exclusive op-ed by Grégoire Person, co-founder of Cyplom, on a little-discussed consequence of the recodification of French VAT into the Code of Taxes on Goods and Services (Code des impositions sur les biens et services, "CIBS").
The recodification is announced as being carried out at constant law. Yet the second paragraph of Article L. 211-36 of the CIBS brings into domestic law a test drawn from European case law: a supply of goods occurs on physical delivery where the acquisition of ownership follows automatically from the contract, in particular by reason of the absence of an economically rational alternative choice
That test comes from the Mercedes-Benz Financial Services judgment (CJEU, 4 October 2017, Case C-164/16) and has been applied by the French courts (Bordeaux Administrative Court of Appeal, 16 June 2020, no. 18BX02182), but it had never been expressly written into the French administrative guidance.
The practical consequence: certain finance lease and hire-purchase contracts, currently treated as leases until the purchase option is exercised, could be characterised as supplies of goods on delivery of the asset from 1 January 2027. The corrective ordonnance of 27 July 2026 postponed the entry into force of Book II of the CIBS but left this wording untouched.
The points the op-ed highlights
It sets out the unusual situation that results: the BOFiP update of 8 July 2026 (BOI-TVA-CHAMP-10-10-40-10) restates the traditional analysis under the French Tax Code, while the CIBS, due to apply six months later, expressly enshrines the case law test.
Above all, it identifies the hard question left unanswered: the treatment of contracts already running, and the possible asymmetry between a lessee treating physical delivery as a supply and a lessor accounting for VAT on exercise of the option. Transitional administrative guidance is called for without delay.
For finance departments, three workstreams are proposed: map the contracts and apply the financial test from the 2017 judgment, quantify both scenarios in cash flow and deduction terms, then agree a consistent treatment with the counterparty.
Also on this site
The same recodification requires the VAT wordings on invoices to be reworked before the tolerance expires on 30 June 2028. We explain why the Directive is the better reference there in VAT wording on invoices: cite the Directive rather than the CIBS.
Related service
View the service →
A question on this topic?
Talk to one of our lawyers about your situation.
Book an appointment →In the media
Our other appearances
Op-eds, interviews and quotes: read our lawyers' analysis in the press.

Let's discuss your VAT matter
Advisory, tax audits, litigation, or digital tax projects: describe your situation, and we will get back to you shortly.