logo cyplom
Lawyers - VAT
Innovative
Partners of their clients

The law firm dedicated to VAT and digital tax compliance

Consulting, litigation, and automation tools
to secure your business

Secure your business

Manage your taxation calmly

Manage your taxes with peace of mind

Structure your projects

Save money

Optimize your cash flow
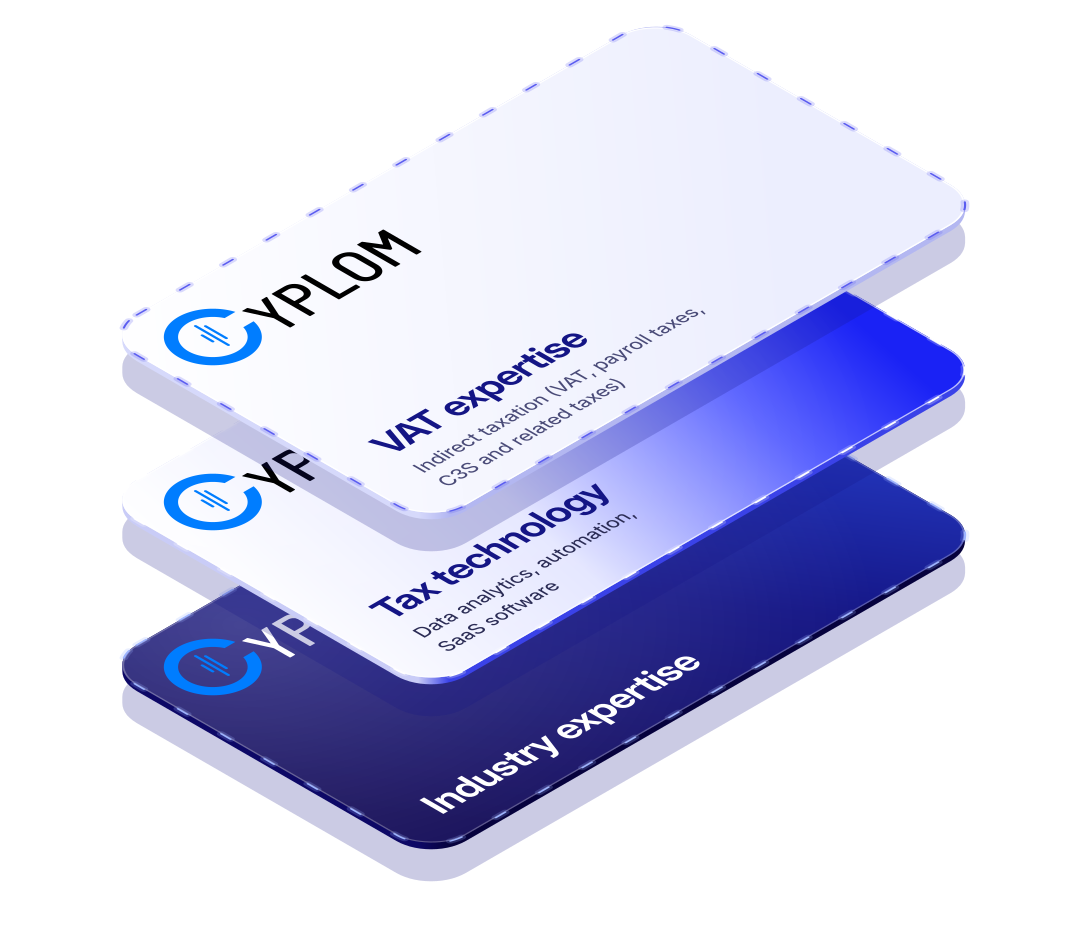
Illustration showing the firm's three pillars: VAT expertise, Tax technology, and Sector expertise

500+ clients supported,
from startups to CAC 40 groups

Excellent

VAT & Indirect Tax

Décideurs 2026

Excellent

Computerised Accounting Audits

Décideurs 2026

We publish in their journals or provide training for them

1

Innovative by nature

We integrate and develop tailor-made solutions to simplify and automate your tax processes, thus ensuring effective management of your taxation.

2

Predictable fees

Our flat rates offer our customers total transparency

3

Business partner

We offer concrete tax solutions and personalized support by taking part in the operational choices of our clients.

Our expertise

Our areas of expertise

Comprehensive VAT expertise, powered by technology

Legal advice, automation tools, and training:
explore our services for every need

The team that lives and breathes VAT

Our team

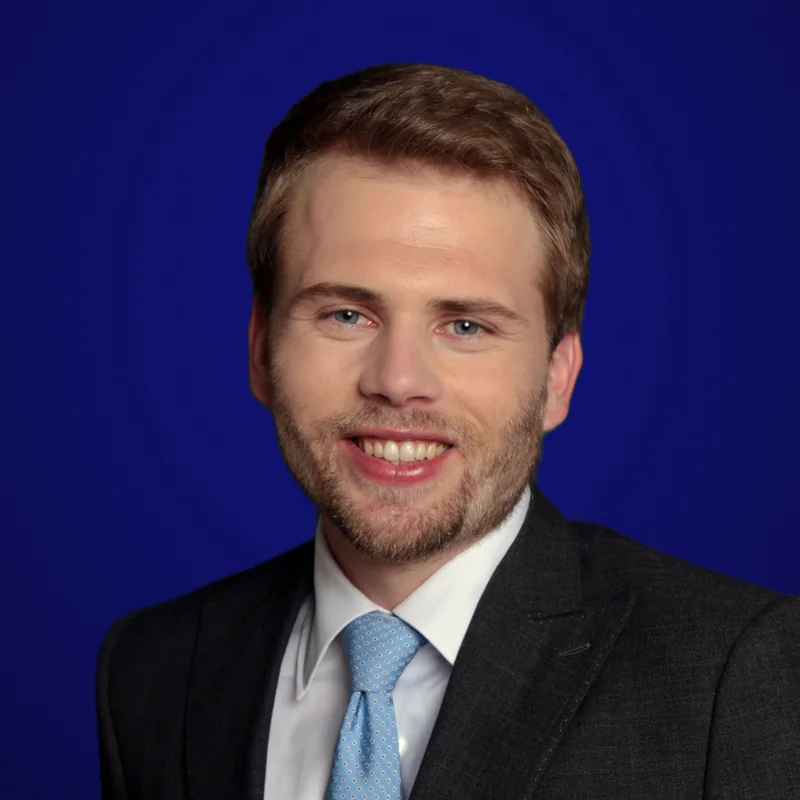
Profile of Grégoire Person, partner and co-founder
Grégoire Person
Partner - Co-founder
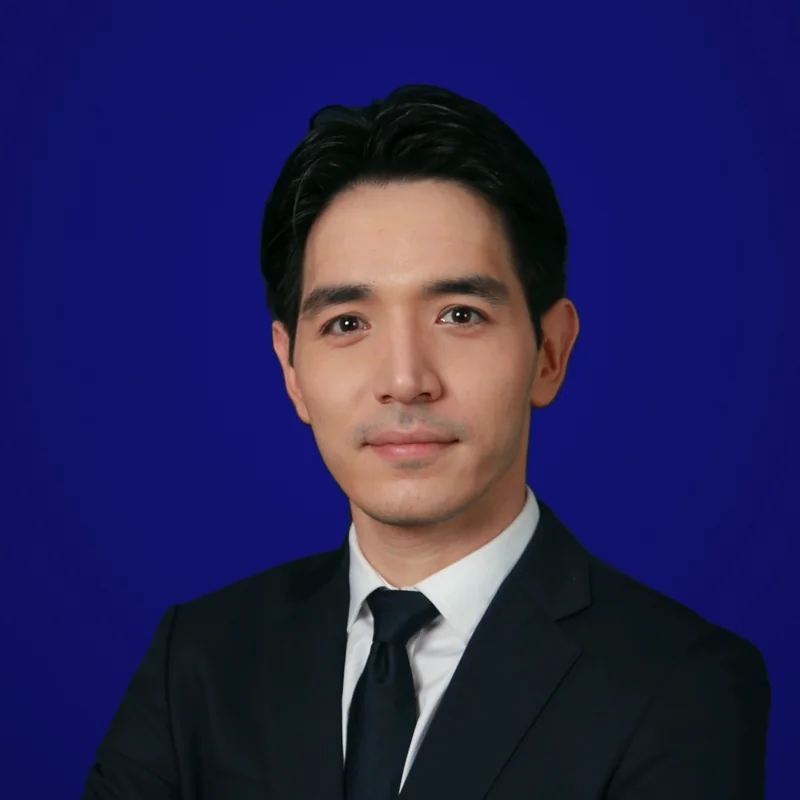
Profile of Thomas Le Boucher, partner and co-founder
Thomas Le Boucher
Partner - Co-founder
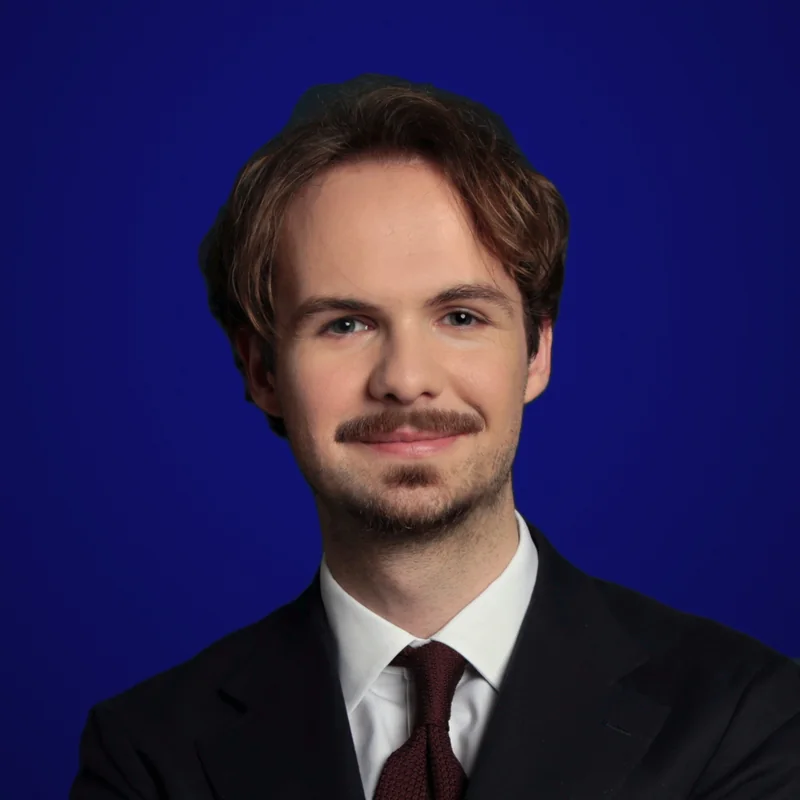
Profile of Corentin Auve, tax specialist
Corentin Auve
Tax Specialist
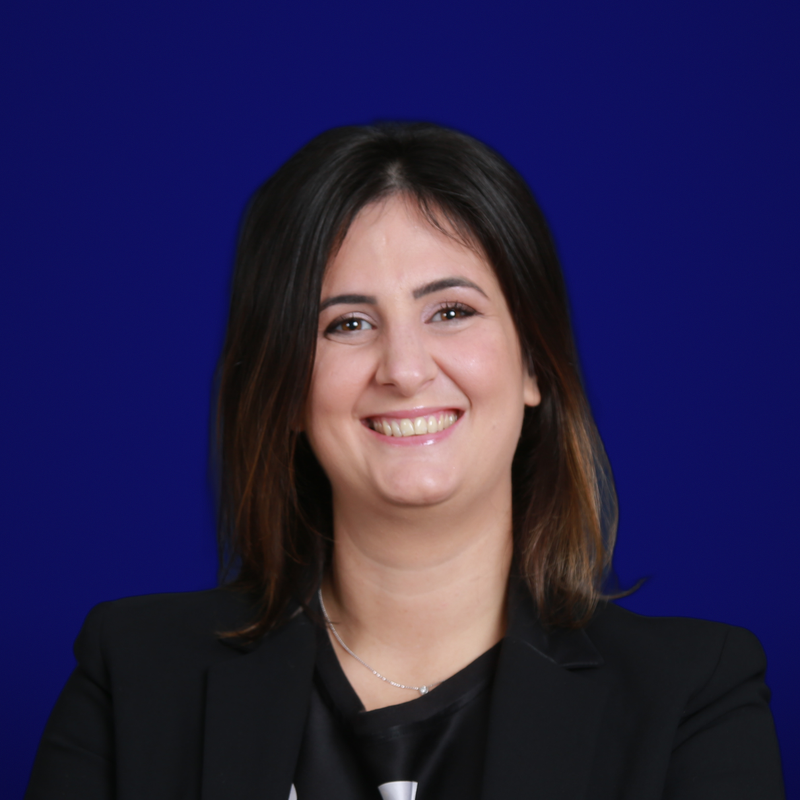
Profile of Débora Grimaldi, tax specialist
Débora Grimaldi
Tax Specialist
Insights and analysis

Our
news

The simplified VAT regime ends on January 1, 2027, bringing automatic transition to the standard regime, new filing schedules, cash flow implications, and e-reporting obligations from September 2027.

End of France's simplified VAT regime in 2027: the timing changes more than the amount

The simplified VAT regime ends on January 1, 2027, bringing automatic transition to the standard regime, new filing schedules, cash flow implications, and e-reporting obligations from September 2027.
On July 16, 2026, the Conseil d'État annulled the tax ruling that subjected children's audiobook players to a 20% rate. The device is merely the physical medium for the audiobooks it contains, meaning the 5.5% rate applies.

VAT on books and audiobook players: 5.5%

On July 16, 2026, the Conseil d'État annulled the tax ruling that subjected children's audiobook players to a 20% rate. The device is merely the physical medium for the audiobooks it contains, meaning the 5.5% rate applies.
French VAT leaves the Tax Code for Book II of the CIBS on 1 January 2027, and the old invoice wordings remain accepted until 30 June 2028. Why we recommend citing Directive 2006/112/EC rather than the CIBS: wording mapping, VATEX codes and a remediation timetable.

VAT wording on invoices: cite the Directive rather than the CIBS

French VAT leaves the Tax Code for Book II of the CIBS on 1 January 2027, and the old invoice wordings remain accepted until 30 June 2028. Why we recommend citing Directive 2006/112/EC rather than the CIBS: wording mapping, VATEX codes and a remediation timetable.
The Conseil d'État denies the export VAT exemption to a supplier whose customs documents name, not its French purchaser, but that purchaser's own customers. What this means for chain sales and the food and drink industry.

French export VAT exemption: the consignee named on the customs document can defeat the first seller's exemption

The Conseil d'État denies the export VAT exemption to a supplier whose customs documents name, not its French purchaser, but that purchaser's own customers. What this means for chain sales and the food and drink industry.
The ruling of 19 August 2026 holds that whether a good was physically used is irrelevant to the VAT margin scheme. We analyse its scope for deadstock sneakers, graded trading cards, sealed products and cellared wine.

VAT margin scheme: an unopened bottle or a sealed sneaker box is still a second-hand good

The ruling of 19 August 2026 holds that whether a good was physically used is irrelevant to the VAT margin scheme. We analyse its scope for deadstock sneakers, graded trading cards, sealed products and cellared wine.
In July 2026, the DGFiP published a practical guide to getting started with electronic invoicing: 29 Q&As that confirm there will be no further delays while outlining how to manage potential issues. We have analyzed the full text and identified the practical implications for businesses.

Electronic invoicing: what the DGFiP onboarding guide actually allows as of September 1, 2026

In July 2026, the DGFiP published a practical guide to getting started with electronic invoicing: 29 Q&As that confirm there will be no further delays while outlining how to manage potential issues. We have analyzed the full text and identified the practical implications for businesses.
Contact us

Let's discuss your VAT matter

Advisory, tax audits, litigation, or digital tax projects: describe your situation, and we will get back to you shortly.

Thomas Le BoucherGrégoire Person
Thomas Le Boucher and Grégoire Person, partners and co-founders of the firm.
Email
contact@cyplom.com
Phone
+33 1 84 20 73 25
Our offices
103 rue La Boétie, 75008 Paris
Thanks for your message! We will get back to you quickly!
Oops! Something went wrong while submitting the form.